AGM recap: CEO observations, portfolio performance and positioning
Quick read:
- Alison Gibson, CEO and Managing Director of AMCIL, outlined the key areas of focus for the Company, including refining the investment process and communicating AMCIL's value more effectively.
- The investment team provided an update on performance and changes to portfolio construction.
- The AGM also covered themes observed during reporting season, including takeover activity and dividend outcomes.
At the Annual General Meeting (AGM) held on 1 October 2026, shareholders heard from CEO and Managing Director of AMCIL, Alison Gibson, in her first AGM address since rejoining the business in July 2026. The investment team also provided an update on FY26 performance, market conditions and portfolio positioning under recently appointed Portfolio Manager, Winston Chong. In this article, we recap the key discussion points.
CEO Address
CEO and Managing Director, Alison Gibson, reflected on why she chose to return to AMCIL and outlined the areas identified for improvement.
For Alison, returning to AMCIL was about purpose, people and the opportunity to work directly for shareholders. She highlighted the Company's strong foundations and AMCIL's ability to provide shareholders with an actively managed and differentiated, high-conviction portfolio of quality companies.
Building on those foundations, Alison outlined two areas of focus. The first is investment performance. While acknowledging performance for FY26 was disappointing, she reinforced that AMCIL has delivered outperformance over the long term and that increased market volatility is creating opportunities for long-term investors willing to step into periods of dislocation and invest in quality companies at attractive valuations.
The second is communicating AMCIL's value proposition more effectively to current and future shareholders. With AMCIL trading at a discount to net tangible assets (NTA), investors currently have the opportunity to buy a high-conviction portfolio of quality companies at around 85 cents in the dollar (as at 1 October 2026).
Alison concluded with confidence in AMCIL's distinct role within the LIC group as its most agile portfolio, with a mandate to back conviction in companies and sectors through the cycle.
FY26 results and addressing recent performance
The team also provided a recap on FY26 performance. AMCIL's profit for FY26 increased to $6.9 million, up from $6.7 million in FY25. Shareholders received a total fully franked dividend of 4.0 cents per share, including a 0.5 cent special dividend.
The Board acknowledged that FY26 was a challenging year for AMCIL. The portfolio delivered a return of approximately -10% including franking, compared with 7.2% for the S&P/ASX 200 Accumulation Index, including franking.
AMCIL's underweight exposure to the materials and energy sector and overweight exposure to information technology and healthcare weighed heavily on the relative performance of the portfolio. Several disappointing stock-specific outcomes also impacted returns for the year.
While recent results have been below expectations, AMCIL has delivered outperformance over the long term. The team remains confident in the underlying quality of portfolio holdings and believe the changes being made to portfolio construction and risk management provide a stronger foundation for future performance.
Market update
The investment team discussed the key themes from the recent reporting season that are influencing both market conditions and portfolio opportunities.
Relief rallies in holdings such as CSL and Cochlear followed results that were better than market expectations, helping recover some earlier price weakness. Consumer softness remained another key theme, particularly across discretionary spending categories. While some parts of the market continue to face headwinds, the investment team noted that periods of weakness can create opportunities to invest in quality companies at more attractive valuations.
Reporting season also saw heightened takeover activity from offshore companies or private capital, signaling opportunities emerging in selected sectors where the market remains cautious.
Dividend outcomes from a number of portfolio holdings in the August reporting season, including Woolworths, Telstra, Transurban and BHP, were stronger than expected and reflected AMCIL's focus on companies with resilient earnings and strong balance sheets.
Looking ahead, the investment team noted that while the broader market appears modestly expensive, significant valuation differences across sectors and companies continue to create opportunities for active investors.
Portfolio update and positioning
Portfolio Manager, Winston Chong, provided an update on portfolio positioning and the changes implemented.
Conviction remains at the heart of AMCIL's strategy and is underpinned by the Company's investment thesis: the people, the business, and the valuation. Over the past six months, the investment team has reviewed every holding, resulting in a more concentrated portfolio and larger active positions behind the team's highest-conviction ideas. AMCIL's structure allows the team to step into market volatility and remain focused on the long term when conviction remains strong.
Examples of this included a new position in AUB Group and an increased position in Technology One, where short-term concerns around AI disruption created opportunities to build exposure to businesses the team believes have strong long-term prospects.
The team also increased positions in Auckland Airport and Woodside, taking advantage of short-term market dislocations with confidence in the underlying investment case.
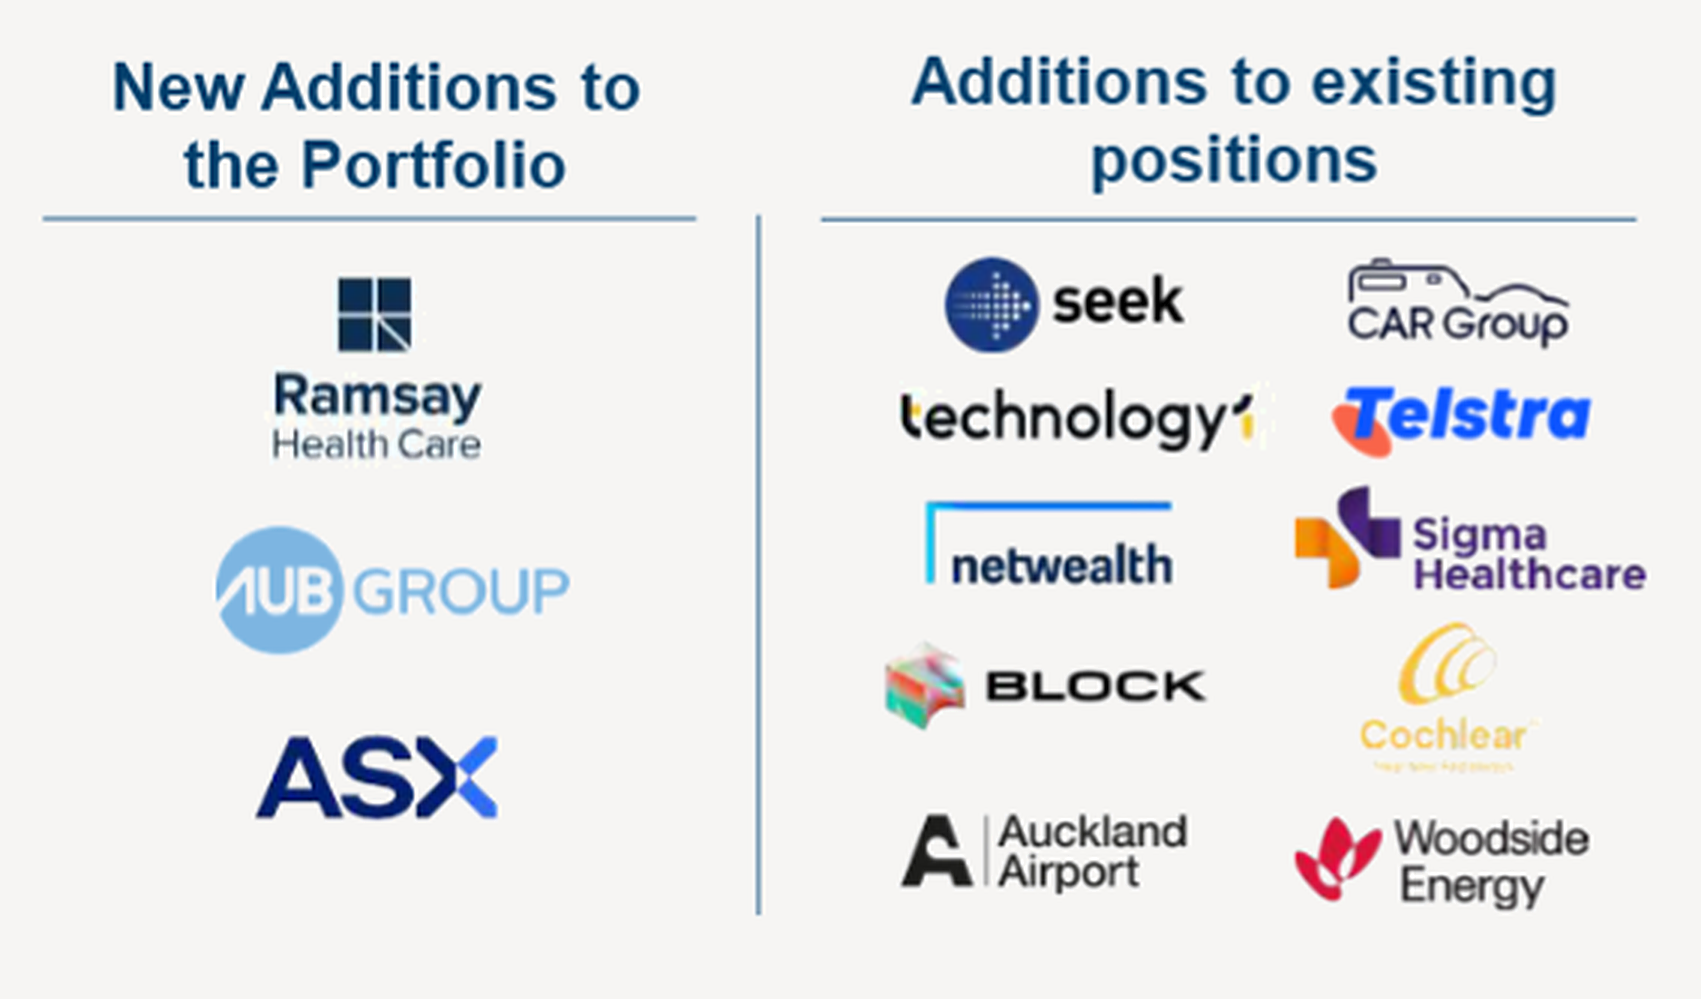
Having tested the investment thesis and conviction behind every stock in the portfolio, the team is confident that a more focused portfolio positions AMCIL to deliver on its investment objectives over the medium to long term.
Looking ahead
AMCIL enters the new financial year with a more concentrated portfolio, stronger focus on conviction and enhanced risk management. Combined with strong foundations and a high calibre team, it is well positioned to deliver improved outcomes for shareholders.
Shareholders can view the full AGM presentation for further information.